

 “I must give the British people a very simple instruction: you must stay at home.”
It’s been five years, yet those words still land like an unexpected letter from HMRC: sharp, sobering and enough to send a shiver up the spine.
Who’d have thought that one grim address to the nation would be the starting gun for the most bizarre, challenging and unexpectedly transformative chapter in our collective lives?
From makeshift home offices perched on ironing boards to Zoom fatigue, ‘You’re on mute’ becoming the world’s most uttered phrase, sudden moves to the countryside, Cockerpoos everywhere and the Great Sourdough Bread Bake-Off of 2020, life as we knew it was turned on its head.
There are positives among the negatives as the workforce has opened to a whole new section of talent
And, despite the masks having come off, we’re still living with the echoes.
Whether it is working remotely, struggling to get people into the office, paying off a bounceback loan, wondering how you deal with training new people, watching the toll it all took on the mental health of your children and how they interact with the world now, or even still revelling in new-found freedoms you never thought possible — our industry, like many others, has changed.
Of course, there are positives among the negatives as the workforce has opened to a whole section of talent who could never fit in with the 9-to-5 office world. But it has also — and I am here to be shot down — tipped a bit of sand into the UK’s productivity engine.
The masks are off but we’re still living with the echoes
As brokers, we’re the lucky ones — we can work anywhere with a laptop and caffeine. But many are still trying to work out their place in the ‘new normal’, feeling isolated and overstressed without realising it. It is a tricky paradox of emotions.
Trump’s tariffs
Still, the world moves on… or does it?
The same orange-hued fella is in power across the pond and, as I sit by the fire in the early hours of what’s being coined ‘Liberation Day’, I can’t help but imagine a confused groundhog peeking out, sniffing the cool night air and promptly heading back in, muttering, ‘WTF….’
We can’t afford for the BoE to sit on its hands for too long
Tariffs? You may already know if they’ve hit us. The big question is, will they light the inflationary fuse again or push us closer to a rate-cutting panic button? Maybe they’ll vanish altogether, like Liz Truss’s credibility.
And so, we welcome April, AKA ‘Angry April’. Stamp duty hikes, national insurance increases, rising energy costs, ballooning council tax, and now a bunch of tariffs thrown in for kicks and giggles. Even the minimum-wage hike is a mixed blessing, depending on which side of the payroll you sit.
It was no surprise that the Bank of England (BoE) opted to leave interest rates unchanged amid a swirl of differential data creating a cacophony that is hard to see through. Keeping rates steady was probably the sensible move.
That said, we can’t afford for the BoE to sit on its hands for too long. People need relief, confidence and a reason to hope. I still hold out for two or three rate cuts before we hit the Christmas party circuit. Hope, after all, is never cancelled.
There is an awful lot of potential in the property market
The chancellor, meanwhile, gave her Spring Statement — no Budget here — and this was all about playing to the markets and re-establishing the tight £9.9bn headroom on fiscal rules.
Whether more needs to be done come the Budget proper, time will tell. But, like the BoE, Rachel Reeves has a tricky tightrope to walk, and — I repeat — she needs to be given some real time.
There is much pinned on housing and the easing of planning rules that could add 0.4% to GDP growth, which keeps this policy very much front and centre.
It was interesting to be at parliament to see the launch of Skipton Building Society’s excellent Home Affordability Index, casting a light on how much work needs to be done to improve the prospects of so many attempting to get on the ever-diminishing housing ladder.
Will the tariffs light the inflationary fuse again or push us closer to a rate-cutting panic button?
That said, there is an awful lot of potential in the property market and, with a bit of goodwill and a willingness to walk across divides, if all parties come together to effect a long-term plan, real change and progress can be made.
Meanwhile, of course, everyone is still paying close attention to those deviously delectable money markets, where three-month Sonia has shimmied down 0.08% to 4.61%, while swaps have decided they are getting bored and have risen to get everyone’s attention again.
Since the previous column:
2-year money is up 0.04% at 3.98%
3-year money is up 0.06% at 3.93%
5-year money is up 0.09% at 3.92%
10-year money is up 0.16% at 4.07%
There have been interesting moves in our lovely mortgage market, with Santander kicking things off and becoming the first large lender to improve residential affordability rates since the FCA’s recent words of encouragement.
In reducing them by 0.75%, it has made them the lowest they’ve been since 2022, and I expect other lenders to follow suit, which would make a real difference to many prospective borrowers. There really does seem room for more sensible risk now.
Next up, and getting two thumbs-up, is tech darling Generation Home, which is the latest lender to prove that innovation is alive and well. Its New Home Boost is like a more mature Help to Buy scheme after the crazy university years, now settling down and looking for a proper job. With no interest on the loan part, no additional equity to pay if repaid in the first five years, then capped at twice the loan amount, it ticks a lot of boxes.
Santander is the first large lender to improve residential affordability rates since the FCA’s recent words of encouragement
In other news, Nationwide has increased its maximum LTV on interest-only to 75%, as well as increased the maximum LTV for foreign nationals without indefinite leave to remain to 85%. It has also removed the need for a 25% deposit to be provided from their own resources.
Virgin Money has revamped its Retrofit Boost mortgages, now giving up to £10,000 cashback for those making energy-efficiency improvements, while Accord’s Cascade Score range is available for new-build properties up to 90% LTV.
Meanwhile, Atom Bank has raised its maximum LTV for near-prime products to 90% from 85%.
Cuddly Coventry has increased its maximum buy-to-let lending exposure from £2m to £2.5m, as well as raised the number of properties mortgaged with it from five to seven, with the total number of mortgaged rental properties clients can hold in their portfolio rising from 10 to 15.
Virgin Money has revamped its Retrofit Boost mortgages
Precise has increased its maximum lending to 95% LTV and raised its maximum loan size to £5m, as well as reduced stress rates.
And a big cheer to Hodge, which has announced that it is to raise its broker procuration fees from 0.45% to 0.55% across its residential products, reflecting its commitment to fair compensation and improving value for brokers and customers.
I shall raise a glass to that, my friends!
You Know What Really Makes Me Smile?
Yesterday I had the great fortune, with a colleague, to attend a school in East Finchley to join The Money Charity in a workshop we had sponsored with the aim of educating and engaging kids in the subject of finance and money.
Basically, they took over the maths lesson of Year 9 kids and ran a workshop called ‘Getting Paid and Spending it’.
I would urge everyone to see what they can do to help financially educate the next generation
It covered how to read a payslip, how income tax works and budgeting, all designed to introduce young people to each topic in an engaging way that is relevant to real life.
It was amazing to watch a range of very different, and differently behaved, kids engage in the lesson from the off, asking interesting questions and enjoying something a little bit different.
It clearly made a difference in trying to change young people’s perception of money.
I would urge everyone to see what they can do to help financially educate the next generation.
Hero to Zero
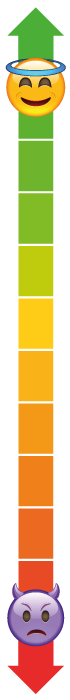 Santander — improving affordability
Hodge — increasing proc fees
Generation Home’s New Home Boost — innovation, yay!
Over half of freelancers saying that their employment status has ‘negatively impacted’ their mortgage ambitions — more work to be done here
Stamp duty changes — an opportunity missed
‘Liberation Day’ – don’t even…
This article featured in the April 2025 edition of Mortgage Strategy.
If you would like to subscribe to the monthly print or digital magazine, please click here.
The post Market Watch: Five years on from lockdown… appeared first on Mortgage Strategy.